News · 11 October 2026 · 5 min read
Sydney auctions cleared 46 per cent. Here is the decision if you hold equity and a pre-approval
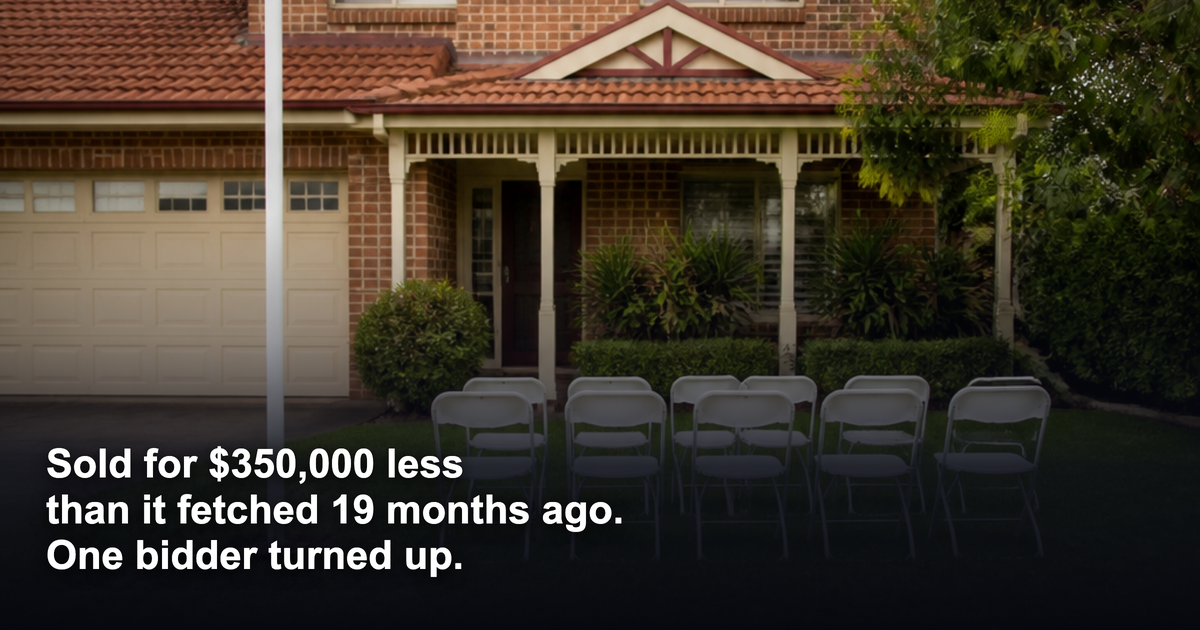
On Saturday a five-bedroom house in Sydney's north-west sold at auction for $2,525,000.
The number
On Saturday a five-bedroom house in Sydney's north-west sold at auction for $2,525,000.
It last sold in March 2025 for $2,875,000. Before that, in April 2024, it changed hands for $3,161,000, according to the Sydney Morning Herald's weekend auction report.
That is $350,000 below its last sale and $636,000 below the one before it. One bidder registered. The reserve had been set around $2.6 million and was adjusted on the day so the home would sell.
Hold that house in your mind, because it carries the whole lesson of this weekend.
What changed across the city
Sydney had 807 auctions scheduled last week. By Saturday evening Domain had a preliminary clearance rate of 46 per cent from 472 reported results. Another 176 auctions were withdrawn, and withdrawn auctions count as unsold.
That is the lowest early read this year. The previous low was 47 per cent in the second-last week of June, when buyers paused to think about the federal budget's changes to the tax treatment of investment properties. Since then the cash rate has been lifted for the fourth time this year, and the Herald notes the preliminary figure will probably fall further as late results arrive.
The texture of the weekend matters as much as the headline rate.
In the inner west a renovated terrace with a price guide of $1.62 million and a reserve of $1.7 million drew one bidder. She opened at $1.5 million and the price was negotiated up on the auction floor to $1.58 million. It sold, $120,000 under the reserve.
In Abbotsford, vendors of a waterfront apartment cut their $2.35 million reserve when bidding stalled at $2.32 million. A late bidder then pushed it to $2.34 million and the owners countered with a $10,000 rise. They got their original number, which the selling agent described as "rare in this market". The same agent called it "the most challenging market I have seen in my whole career, in 30 years", and added that if a property is priced correctly, it will sell.
Another agent put it more bluntly: "Gone are the days when an agent quotes the price and it goes above. Buyers are coming to auction even though they are under the quote price."
What this means if you have equity or cash
For three years the auction floor belonged to vendors. Guides were a floor, reserves sat above them, and the buyer who hesitated lost.
That has flipped. One-bidder auctions mean the price is being set by negotiation, often before the auctioneer opens his mouth. Reserves are moving down to meet the one person in the room. Vendors who need to sell are selling at the number the market offers.
If you own your home, hold usable equity and have a current pre-approval, you are now the scarce party in most of these rooms. You can bid under the guide and be taken seriously. You can ask for terms. You can walk away from a contest and find the same leverage at the next one.
Four rate rises this year cut the other way. Your borrowing capacity is lower than it was in January and your holding cost on any purchase is higher. The leverage is real, and so is the cost of using it.
The decision, and the trade-off almost nobody prices
The obvious response to a 46 per cent weekend is to wait for the bottom.
Nobody will tell you when that is. The Herald expects the clearance rate to drift lower as results come in, and the cash rate has already moved four times. A bottom is only visible after it has passed, by which time the one-bidder auctions have become three-bidder auctions and the discount has gone.
The less obvious response is to buy because prices are soft. That is where the north-west house earns its place in this article.
The buyer who paid $2,875,000 in March 2025 was also buying at a discount. That price was about 9 per cent below the April 2024 sale of $3,161,000. They had the same leverage you have now. They used it, and nineteen months later the house cleared at a further 12 per cent below what they paid.
The discount was never the protection. The asset was the exposure.
Two homes on the same weekend, in the same city, tell the same story in opposite directions. One sold $120,000 under reserve to a single bidder. One sold at full reserve after three registered buyers fought for it. Same clearance rate. Same rate cycle. Different streets, different buyer depth, different outcome.
So the real decision for someone with equity is whether the thing you are negotiating hard on will still have buyers behind it when you need them, in 2028 or 2031, in a market that may look nothing like this one. Whether this weekend was the bottom is a much smaller question.
The Ripehouse reframe
A weak weekend is an input. Nobody should mistake it for a strategy.
We see this in every cycle. Two streets in the same suburb can be having completely different outcomes at the same time, and the clearance rate tells you nothing about which is which. Days on market, vacancy, the depth of the buyer pool and the type of household the street attracts decide whether a 12 per cent discount is a bargain or a warning.
That is why we do not buy on timing. We buy on structure: the right asset, on the right street, measured against outcomes we publish. Across 997 client portfolios since 2021, our clients' median portfolio growth has been 19.0 per cent a year on a 5-year rolling basis, against about 4.3 per cent nationally over the same period (national benchmark: CoreLogic/Cotality). Past performance is not a guarantee of future results.
We don't ask you to take our results on faith. We publish them, including the portfolios that underperformed.
If you have equity and a pre-approval, this weekend did hand you leverage. The expensive mistake is to spend it on the wrong street because the headline said buyers were winning.
Want to see how we test a purchase like this street by street before the leverage runs out? Join Jacob's free live webinar.
General information only. It does not take your objectives, financial situation or needs into account, and nothing here is legal, financial, taxation or investment advice specific to your circumstances.