News · 19 October 2026 · 5 min read
She is $100,000 ahead on her home loan. Her bank is being sold, so her repayments could rise $674 a month
She is 39, lives in Toowoomba with her partner and two kids under ten, and has done the thing every money column tells you to do. She paid extra. For six years, every bonus, every tax refund, every spare few hundred dollars went into the home loan.
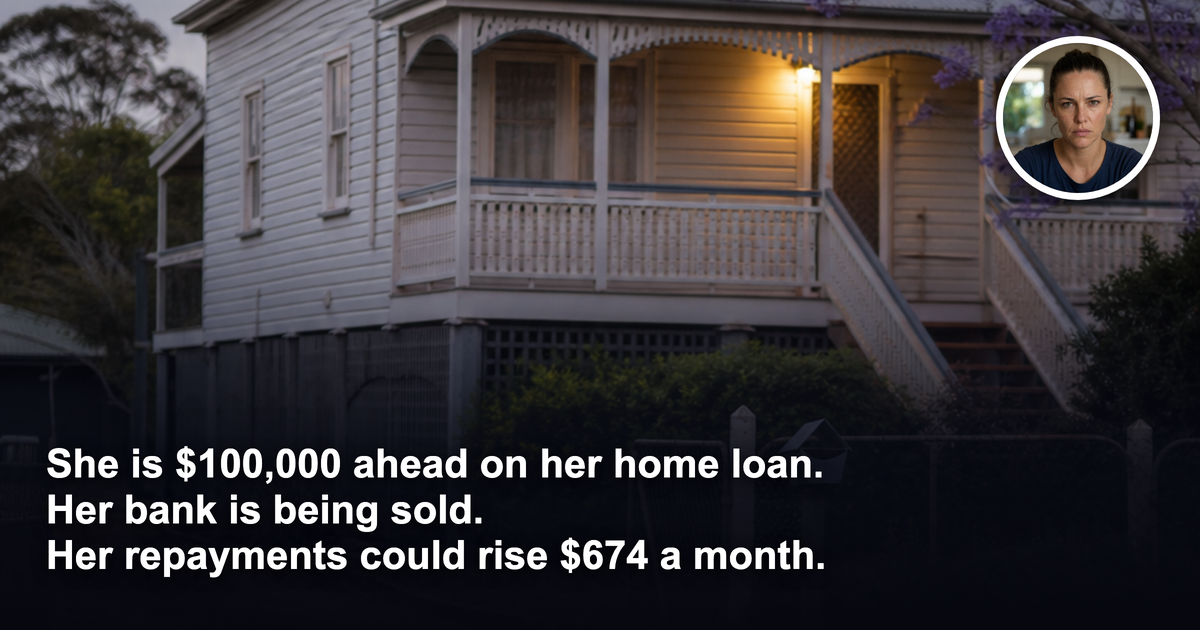
She is 39, lives in Toowoomba with her partner and two kids under ten, and has done the thing every money column tells you to do. She paid extra. For six years, every bonus, every tax refund, every spare few hundred dollars went into the home loan.
The loan is with Suncorp Bank. She owes about $600,000 with 25 years to run, and there is roughly $100,000 sitting in redraw. That buffer was the plan. It was the emergency fund, the deposit for a first investment property, the reason she slept at night.
On 13 October an email arrived. Suncorp Bank is moving its customers onto ANZ's loan platforms, and the email said that for anyone with funds available in redraw, "your minimum loan repayment at ANZ is likely to increase."
She is a composite illustration, not a real person. The numbers come straight from the ABC's reporting and Canstar's worked example. The situation is being lived by thousands of households right now.
The question
"I am $100,000 ahead. I have never missed a payment. Nothing about my loan has changed except who owns the bank. How can my minimum repayment go up by hundreds of dollars a month for doing the right thing?"
The answer: her buffer is about to be counted against her
The ABC published the mechanics on 18 October, and they are simple once you see them.
Suncorp Bank let customers with redraw and cashback facilities reduce their minimum monthly repayments. If you were ahead, your minimum was calculated on what you actually owed.
ANZ does not do that. Canstar's Sally Tindall told the ABC that most banks exclude or discount extra repayments when they set your minimum, so the minimum is calculated on the full contracted balance, even though interest is only charged on the lower amount.
Here is Canstar's example, as reported by the ABC. A borrower owes $600,000 with 25 years left and has $100,000 extra in the loan. On the average owner-occupier variable rate of 6.49 per cent, a minimum calculated on the $500,000 actually owing is $3,373 a month. A minimum calculated on the $600,000 contracted balance is $4,047 a month.
That gap is $674 a month. Every month. For the same loan, the same rate and the same house.
One Suncorp customer told the ABC their email indicated repayments could rise by more than $1,000 a month.
Suncorp Bank's CEO Malcolm Stedman said most customers will see no change, and that those ahead on repayments "may see an increase in their minimum repayments, if they choose to take no action." Ms Tindall agreed that increases can be avoided if customers follow the email's instructions.
So the fix exists. The injustice is that the burden of finding it, reading it and acting on it before the transfer in June next year sits entirely with the borrower, who did nothing.
What "variable at the bank's discretion" actually means
Consumer Policy Research Centre CEO Erin Turner put it plainly to the ABC: most Australians have a home loan that is "variable at the bank's discretion", where the bank can change fees and conditions when it suits them.
Read that again if you have ever thought of your loan as a fixed agreement. The rate is variable. The conditions are variable. The way your minimum is calculated is variable. The only thing fixed is your obligation to pay.
More than a million Suncorp customers are set to move to ANZ by 2027. The ACCC originally opposed the acquisition in 2023 on the grounds that less competition would give customers a worse deal. The Australian Competition Tribunal set that aside and both governments approved it. Whatever you think of that decision, the people now reading repayment emails at the kitchen table were not in the room.
What it means for you, even if you have never banked with Suncorp
The expensive mistake is assuming your loan structure belongs to you.
It does not. It belongs to the lender's current policy. A redraw buffer is a bank feature, not a legal right. An offset account is a product, and products get discontinued. A minimum repayment is a formula, and formulas change when a platform changes.
Three things are worth checking this week, whoever you bank with:
- Where your buffer physically sits. Money in redraw is inside the loan and subject to the lender's rules. Money in a separate offset account is yours in a way redraw is not.
- How your minimum is calculated. Ask the question directly. Most people have never asked.
- What happens on a transfer. If your lender is merging, being acquired or migrating platforms, the terms you signed may not be the terms you end up with.
None of that is personal advice. It is a checklist for a conversation with your broker or lender, and the Suncorp email is the reason to have it now rather than in June.
The Ripehouse reframe: structure survives a change of bank, timing does not
Most coverage of this story will be rates news. Repayments up, borrowers angry, politicians trading blame.
The point that matters for anyone building wealth through property is different. Her $100,000 buffer was never a strategy. It was a pile of cash in someone else's product, and the product changed.
A structure is something you control. It is the entity that holds the asset, the account the cash sits in, the loan that can be moved without blowing up the plan, and above all the asset itself. A house on the right street in the right suburb keeps performing through a bank merger. Two streets in the same postcode can be having completely different outcomes while their owners read the same email.
Her repayments may rise by $674 a month if she does nothing. That is a serious number. But she still owes $500,000 on a house she can afford, and she is still six years ahead of where she started. Her problem is a structure problem, not a discipline problem, and structure problems are fixable.
The households that get hurt in this story are the ones who built their plan around a feature a bank could withdraw. Build it around the asset, the street and the data instead, and a change of logo on the statement is an admin task, not a crisis.
Want to see how we test a decision like this street by street, before the bank changes the rules? Join Jacob's free live webinar.
If there's a specific street you're weighing up right now, check its Street Score first — it's free, takes ten seconds, and tells you whether that street is pulling the suburb average up or riding on it.
General information only. It does not take your objectives, financial situation or needs into account, and nothing here is legal, financial, taxation or investment advice specific to your circumstances.