News · 10 August 2026 · 4 min read
Weekly Rents: National Up, Capitals Split — Week Ending 9 August 2026
National advertised weekly rents rose $2.85 to $776.53 in the week ending 9 August 2026 — up 7.3% on a year ago — while the Cap City Average slipped $0.32. Sydney houses now average $1,062.02, Darwin is the only capital with double-digit annual growth in both segments, and Melbourne units have converged to within $20 of houses. Full data inside.
(~600 words)
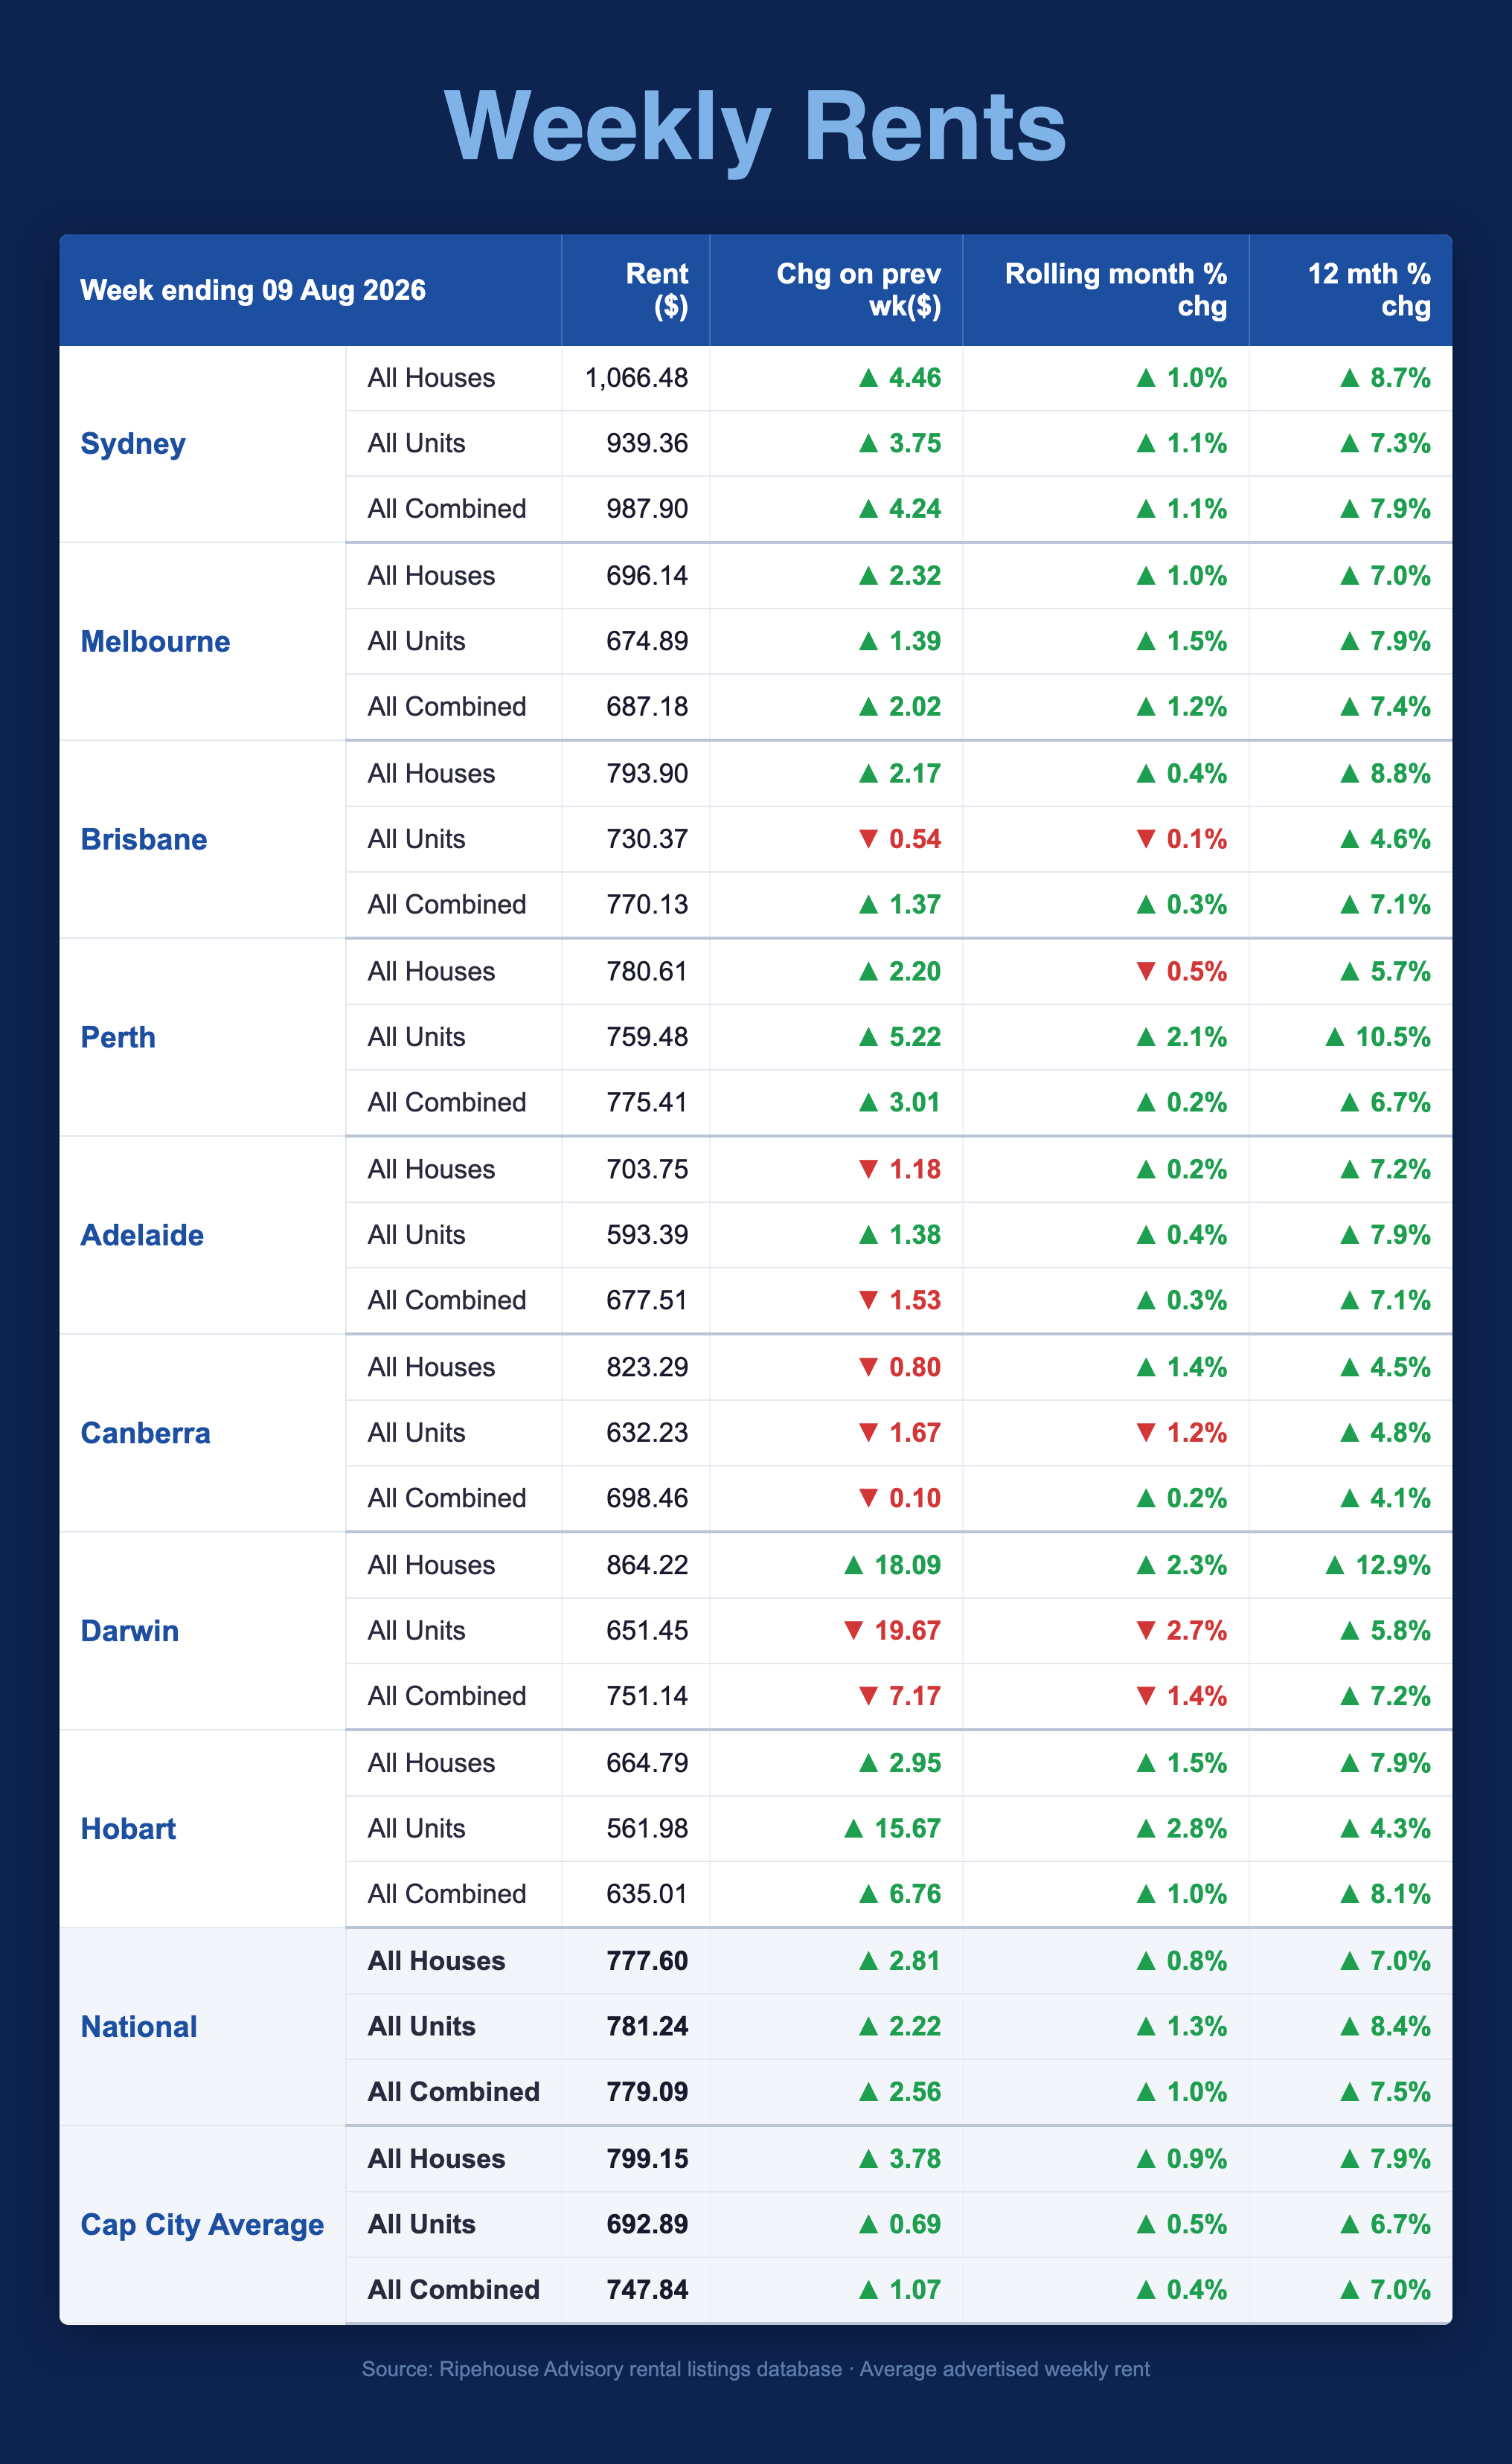
Weekly Rents — Week Ending 9 August 2026
The national combined median asking rent reached $779.09 per week in the seven days to 9 August, up $2.56 on the prior week and 7.5% higher than the same week last year, according to the Ripehouse Advisory rental listings database. The national rolling month sits at +1.0%, indicating the pace of growth is holding rather than fading as we move through winter.
Sydney closes in on $1,000
Sydney remains the most expensive rental market in the country by a wide margin. Houses are now asking $1,066.48 per week, up $4.46 on the week and 8.7% on the year. Units reached $939.36, up $3.75 and 7.3% annually. The combined Sydney median of $987.90 is now within $13 of the $1,000 threshold — a level that would have seemed implausible only a few years ago, and one that continues to push tenants toward smaller dwellings and outer suburbs.
Small capitals deliver the week's biggest moves
The most striking weekly movements came from the smallest markets. Hobart unit rents jumped $15.67 in a single week to $561.98, with the rolling month for Hobart units now at +2.8%. Hobart houses also firmed, up $2.95 to $664.79, and the combined Hobart median of $635.01 is 8.1% higher than a year ago.
Darwin houses added $18.09 to reach $864.22 per week. That segment is now up 12.9% over twelve months — the strongest annual growth of any capital city segment in our dataset. Darwin units moved the other way, down $19.67 to $651.45, a reminder that small sample sizes (134 house and 152 unit listings) make Darwin the most volatile series we publish.
Perth units keep compounding
Perth units rose $5.22 this week to $759.48, taking annual growth to 10.5% — the strongest of any mainland capital segment. Perth houses sit at $780.61, up 5.7% on the year. Notably, Perth units are now asking nearly the same rent as Perth houses, a compression that reflects how tight the unit market has become.
Melbourne and Brisbane steady
Melbourne houses reached $696.14 (up $2.32 on the week, 7.0% annually) and units $674.89 (up $1.39, 7.9% annually). Melbourne remains the most affordable mainland capital for houses, though the gap to Brisbane — $793.90 for houses — continues to widen. Brisbane units were the only mainland segment to fall this week, down $0.54 to $730.37, with annual unit growth of 4.6% now the softest among the mainland capitals.
Adelaide and Canberra flat
Adelaide's combined median slipped $1.53 to $677.51, though annual growth remains firm at 7.1%. Canberra was essentially flat, with the combined median at $698.46 and annual growth of 4.1% — the softest of any capital — consistent with the cooler conditions we have tracked there through 2026.
What this means
National rents are now 7.5% higher than a year ago, with houses at $777.60 and units at $781.24 — units have now edged ahead of houses nationally for the first time in this series. For investors, the picture remains consistent: every capital city is recording annual growth between 4.1% and 8.1% on a combined basis, and the rolling-month figures suggest momentum is intact rather than rolling over. Markets with the tightest supply — Perth units, Darwin houses, Sydney across both dwelling types — continue to deliver the strongest compounding. For tenants, affordability pressure is most acute in Sydney, where the combined median is closing on $1,000 per week.
Data drawn from the Ripehouse Advisory rental listings database, covering 43,318 house and 29,973 unit listings nationally in the week ending 9 August 2026.
The full data — week ending 9 August 2026
| City | Dwelling | Avg Weekly Rent | Chg on Prev Wk | Rolling Mth | Chg 12 Mth |
|---|---|---|---|---|---|
| Sydney | All Houses | $1066.48 | +$4.46 | +1.0% | +8.7% |
| Sydney | All Units | $939.36 | +$3.75 | +1.1% | +7.3% |
| Sydney | All Combined | $987.90 | +$4.24 | +1.1% | +7.9% |
| Melbourne | All Houses | $696.14 | +$2.32 | +1.0% | +7.0% |
| Melbourne | All Units | $674.89 | +$1.39 | +1.5% | +7.9% |
| Melbourne | All Combined | $687.18 | +$2.02 | +1.2% | +7.4% |
| Brisbane | All Houses | $793.90 | +$2.17 | +0.4% | +8.8% |
| Brisbane | All Units | $730.37 | -$0.54 | -0.1% | +4.6% |
| Brisbane | All Combined | $770.13 | +$1.37 | +0.3% | +7.1% |
| Perth | All Houses | $780.61 | +$2.20 | -0.5% | +5.7% |
| Perth | All Units | $759.48 | +$5.22 | +2.1% | +10.5% |
| Perth | All Combined | $775.41 | +$3.01 | +0.2% | +6.7% |
| Adelaide | All Houses | $703.75 | -$1.18 | +0.2% | +7.2% |
| Adelaide | All Units | $593.39 | +$1.38 | +0.4% | +7.9% |
| Adelaide | All Combined | $677.51 | -$1.53 | +0.3% | +7.1% |
| Canberra | All Houses | $823.29 | -$0.80 | +1.4% | +4.5% |
| Canberra | All Units | $632.23 | -$1.67 | -1.2% | +4.8% |
| Canberra | All Combined | $698.46 | -$0.10 | +0.2% | +4.1% |
| Darwin | All Houses | $864.22 | +$18.09 | +2.3% | +12.9% |
| Darwin | All Units | $651.45 | -$19.67 | -2.7% | +5.8% |
| Darwin | All Combined | $751.14 | -$7.17 | -1.4% | +7.2% |
| Hobart | All Houses | $664.79 | +$2.95 | +1.5% | +7.9% |
| Hobart | All Units | $561.98 | +$15.67 | +2.8% | +4.3% |
| Hobart | All Combined | $635.01 | +$6.76 | +1.0% | +8.1% |
| National | All Houses | $777.60 | +$2.81 | +0.8% | +7.0% |
| National | All Units | $781.24 | +$2.22 | +1.3% | +8.4% |
| National | All Combined | $779.09 | +$2.56 | +1.0% | +7.5% |
| Cap City Average | All Houses | $799.15 | +$3.78 | +0.9% | +7.9% |
| Cap City Average | All Units | $692.89 | +$0.69 | +0.5% | +6.7% |
| Cap City Average | All Combined | $747.84 | +$1.07 | +0.4% | +7.0% |
Average advertised weekly rent across all listings available during the week, Ripehouse Advisory rental listings database. Week runs Monday to Sunday; capital cities defined by GCCSA boundaries.
If there's a specific street you're weighing up right now, check its Street Score first — it's free, takes ten seconds, and tells you whether that street is pulling the suburb average up or riding on it.
Market data & R-Scores for locations in this article
Drill Down Into the Markets Mentioned Above
Inspect live monthly R-Scores, median prices, rental yields, and street-by-street scores for the cities and council areas referenced in this article:
Frequently asked questions
Are weekly rents still rising across Australia, and by how much did they move in the week ending 9 August 2026?
Yes. National combined advertised weekly rent rose to $779.09, up $2.56 on the week and 7.5% higher than a year earlier. The rolling month was +1.0%, suggesting growth is still holding through winter.
Why does the article say Sydney is under the most rental pressure?
Sydney remains the most expensive rental market, with houses at $1,066.48 and units at $939.36 per week. Its combined median of $987.90 is now within $13 of $1,000, which the article says is pushing tenants toward smaller dwellings and outer suburbs.
Which capital city segment had the strongest annual rent growth?
Darwin houses recorded the strongest annual growth of any capital city segment in the dataset, up 12.9% over the year to $864.22 per week. The article notes Darwin is also the most volatile market because its sample sizes are small.
What does it mean that national units have edged ahead of houses?
For the first time in this series, national units are slightly more expensive than houses, at $781.24 a week versus $777.60. The article suggests this reflects tight supply in the unit market.
Which markets look tightest if I’m trying to understand where rent growth is most persistent?
The article points to Perth units, Darwin houses and Sydney across both dwelling types as the tightest markets. These segments are described as delivering the strongest compounding, with rolling-month figures showing momentum is still intact rather than fading.
General information only. It does not take your objectives, financial situation or needs into account, and nothing here is legal, financial, taxation or investment advice specific to your circumstances.