News · 4 October 2026 · 5 min read
Weekly Rents: Darwin Houses Up 15.9% a Year - Week Ending 4 October 2026
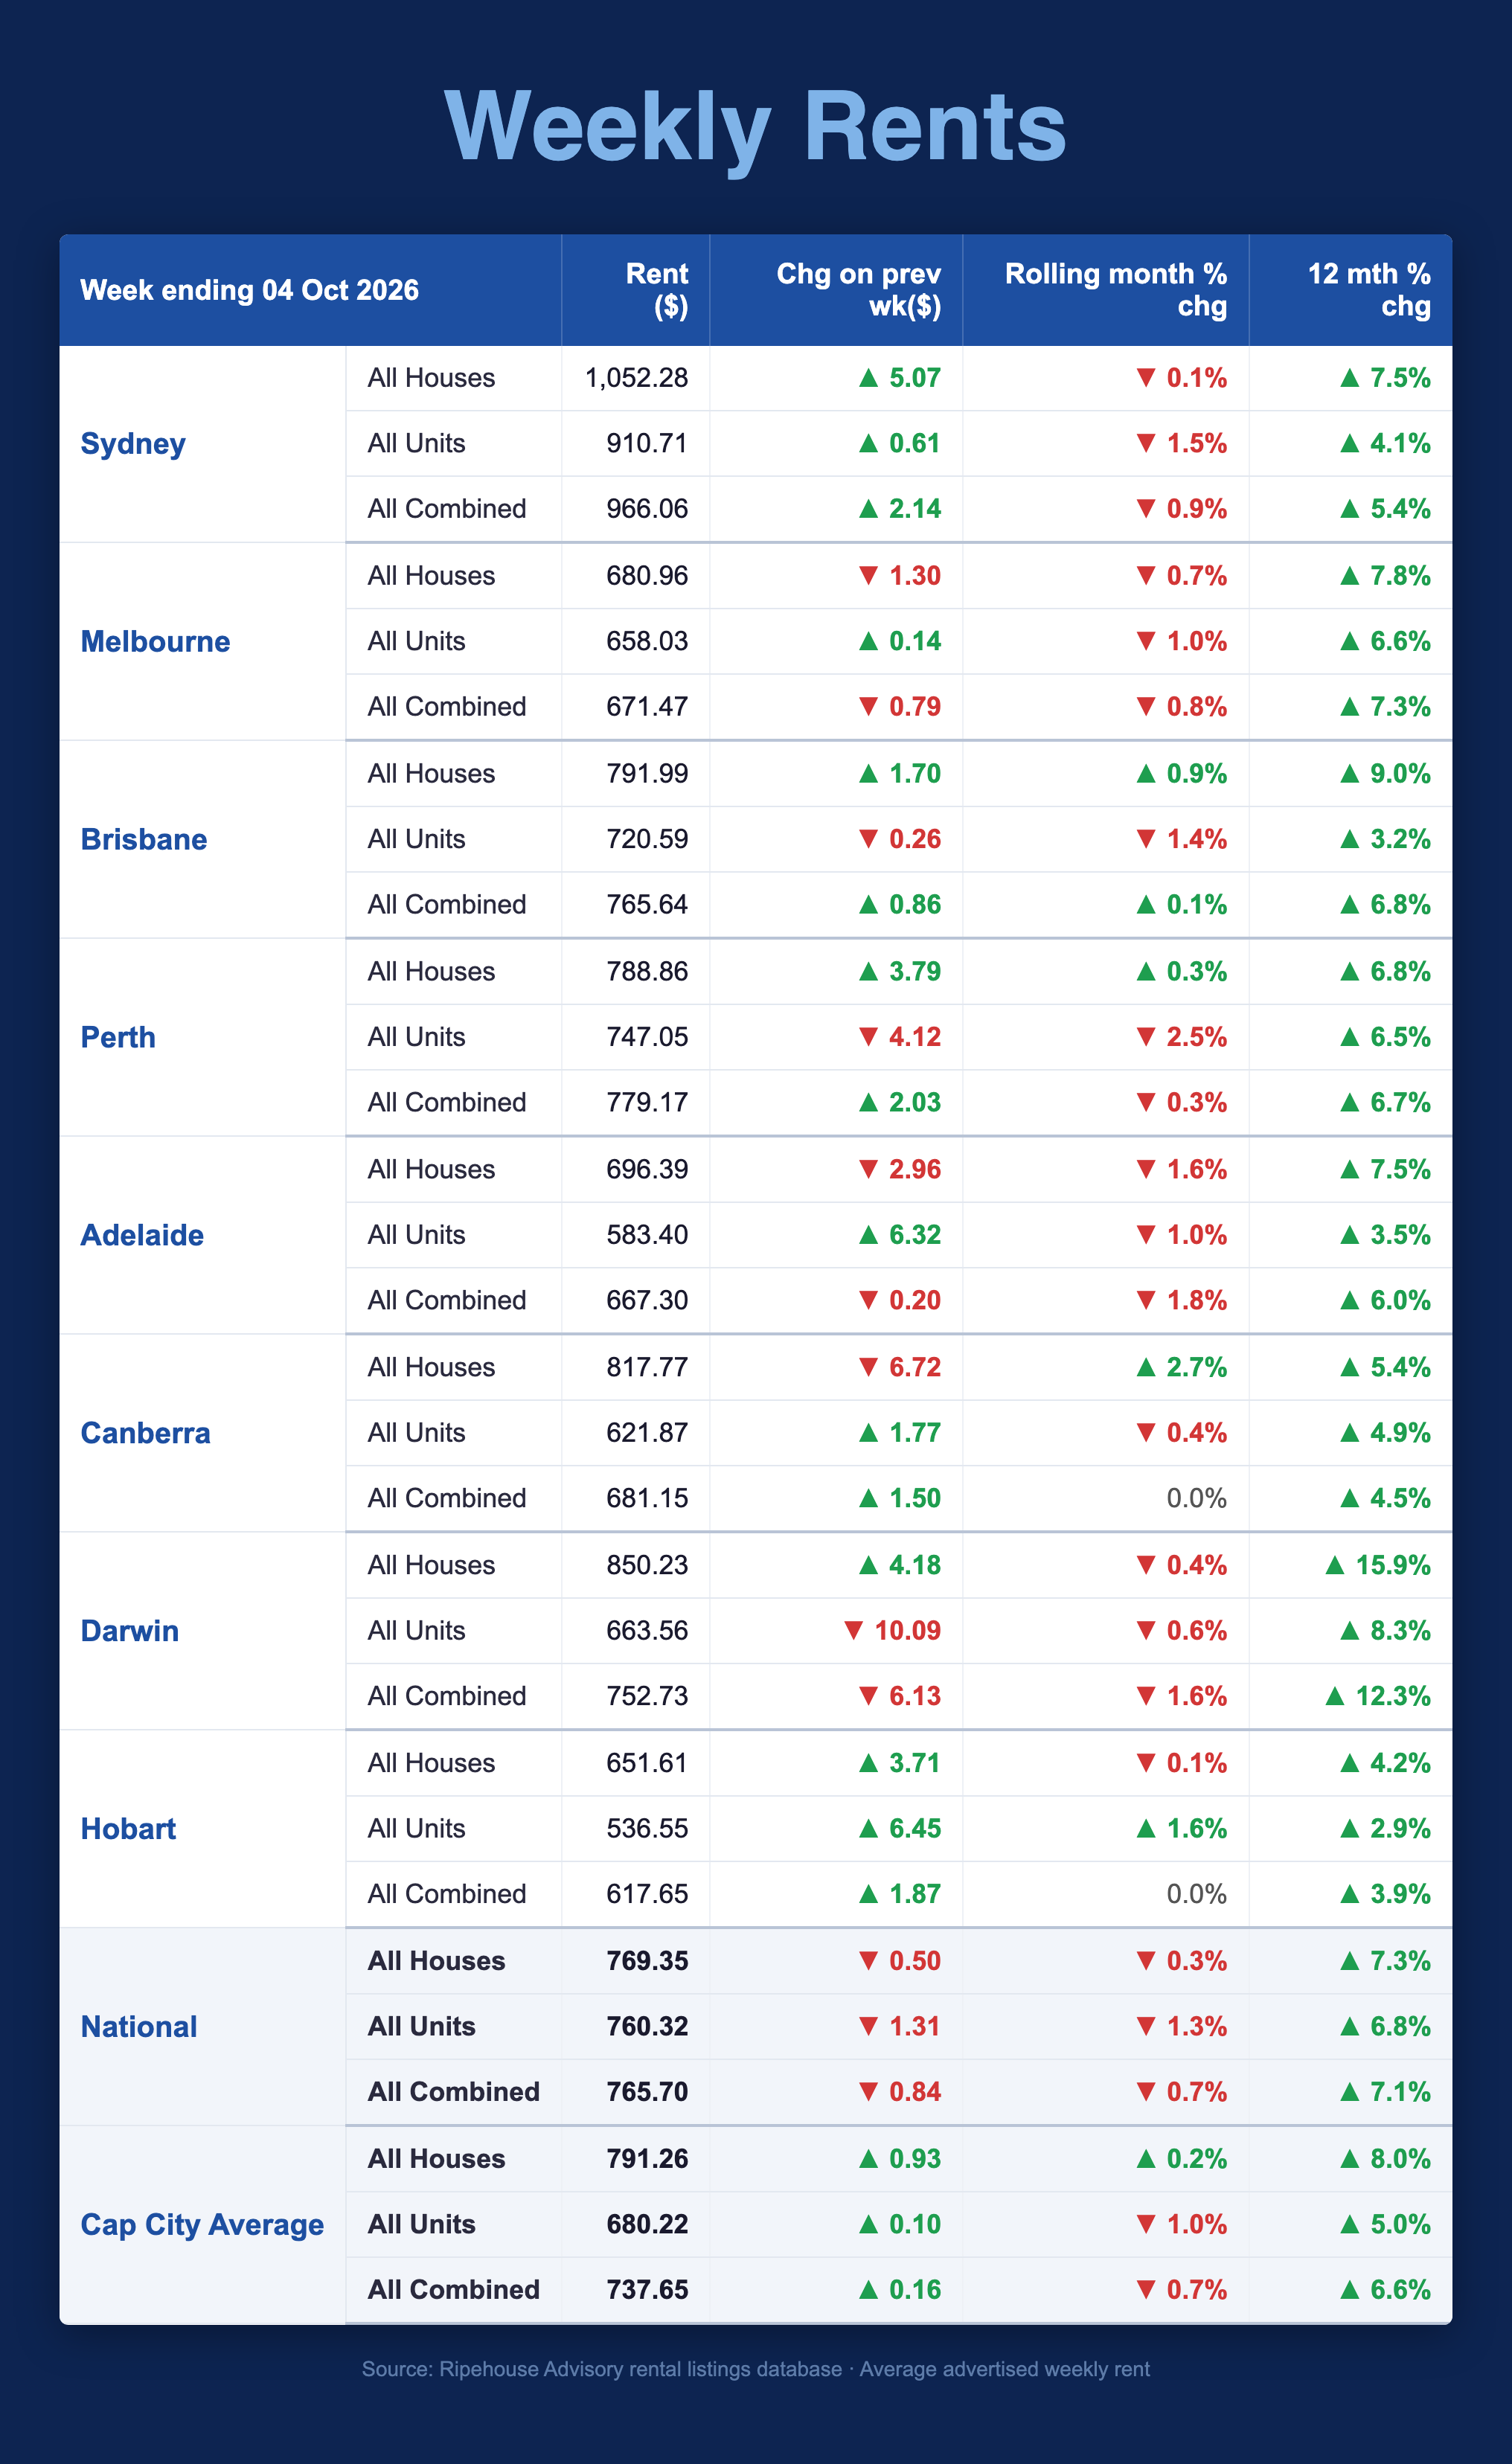
National advertised rents averaged $766 a week in the week ending 4 October 2026. That was down $0.84 on the previous week and 0.7% lower over four weeks, but still 7.1% higher than a year ago. Darwin houses led annual growth at 15.9%. Adelaide had the sharpest four-week combined decline at 1.8%. Gross-yield proxies ranged from 3.64% to 5.87%.
National rents ease short term, annual growth holds
National advertised rents averaged $766 a week in the week ending 4 October 2026. That was down $0.84 on the previous week and 0.7% lower over four weeks. Over the year, though, national asking rents are still 7.1% higher.
Short-term movement and the annual trend can point in different directions. Neither shows a change in the rent on an individual property. A falling average asking rent can simply reflect a different mix of properties on the market, so investors should check comparable listings before changing their cash-flow assumptions.
National houses averaged $769 a week (down 0.3% over four weeks, up 7.3% over 12 months). National units averaged $760 (down 1.3% over four weeks, up 6.8% annually). The capital city average combined figure was $738, up 6.6% on a year ago.
The capital city picture
Combined asking rents ranged from $618 in Hobart to $966 in Sydney.
Sydney houses averaged $1,052 a week, up 7.5% annually. Sydney units averaged $911, up 4.1%. Brisbane houses were one of the few segments to rise over four weeks, up 0.9% to $792, and they are 9.0% higher than a year ago. Brisbane units, at $721, rose just 3.2% annually.
Darwin had the strongest annual growth. Houses averaged $850, up 15.9%, and the combined figure was $753, up 12.3%. Darwin units, however, fell $10.09 in the week to $664, which shows how volatile the smaller markets can be week to week.
Adelaide had the sharpest four-week combined decline among the capitals at 1.8%, with the combined figure at $667. Melbourne's combined figure was $671, down 0.8% over four weeks and up 7.3% annually. Perth was at $779, Canberra at $681 and Hobart at $618. Hobart units rose 1.6% over four weeks to $537.
Listing volumes vary widely. Melbourne recorded 11,147 house listings and Sydney recorded 11,986 unit listings. Hobart had 116 unit listings and Darwin had 214 house listings. Weekly changes in smaller markets rest on far fewer observations.
Asking-rent deciles
New-listing median asking rents were steady across most bands. D2 through D7 were unchanged over four weeks, ranging from $500 to $750. D9 had the largest movement, up 2.70% from $925 to $950. D8 rose 1.22% to $830. At the bottom of the market, D1 eased 2.38% from $420 to $410. D10 stayed at $1,300.
The latest week contained 15,209 first-seen rental observations. Using medians reduces the influence of extreme listings, but it does not remove changes in listing mix.
Gross-yield proxies
The independent-rank gross-yield proxy ranged from 3.64% in D9 to 5.87% in D1. Over four weeks, the proxy moved by between -0.00 and +0.13 percentage points. D10 rose the most, from 3.62% to 3.75%.
This is an independent-rank proxy: mean weekly asking rent in a band × 52 ÷ mean sold price in the matching price band. It is not matched to individual properties, and it is not a net figure. It excludes vacancy, costs, finance and capital gains. Lower-priced bands may show more income relative to price, but treat this as a screening prompt, not a result.
Where rental listings are concentrated
Brisbane (C) (QLD) carried the most advertised rental listings with 957 observations. That is 6.4% of the 14,980 listings matched to a local government area (LGA), at a median of $730 a week. Gold Coast (C) followed with 480 listings at a median of $875. Next were Melbourne (C) with 452 at $680 and Sydney (C) with 400 at $950. Wyndham (C) recorded 280 listings at a median of $518. Listings spanned 350 LGAs.
These counts show rental listing activity, not sales. A high-volume LGA is where listings occurred. It is not a recommendation or evidence of future growth.
What this means
For investors, the annual trend in asking rents is still positive, but the four-week softening is a reminder not to carry last year's growth forward automatically. Test the rent for the exact street and dwelling type. Allow for vacancy, management, maintenance and finance, then compare expected net cash flow with the purchase price.
The opportunity is not the highest decile or the highest yield proxy on its own. It is a property where the specific dwelling, local rental evidence and purchase price still support a defensible cash-flow case. The city table, decile changes, yield proxies and LGA concentration are complementary screening signals, not a buy list.
If you want clarity on your next move, a free 15-minute Investor Decision Review lets you talk through your income, equity, goals and time horizon. It is general information only, not personal financial advice.
The full data — week ending 4 October 2026
| City | Dwelling | Avg Weekly Rent | Chg on Prev Wk | Rolling Mth | Chg 12 Mth |
|---|---|---|---|---|---|
| Sydney | All Houses | $1052.28 | +$5.07 | -0.1% | +7.5% |
| Sydney | All Units | $910.71 | +$0.61 | -1.5% | +4.1% |
| Sydney | All Combined | $966.06 | +$2.14 | -0.9% | +5.4% |
| Melbourne | All Houses | $680.96 | -$1.30 | -0.7% | +7.8% |
| Melbourne | All Units | $658.03 | +$0.14 | -1.0% | +6.6% |
| Melbourne | All Combined | $671.47 | -$0.79 | -0.8% | +7.3% |
| Brisbane | All Houses | $791.99 | +$1.70 | +0.9% | +9.0% |
| Brisbane | All Units | $720.59 | -$0.26 | -1.4% | +3.2% |
| Brisbane | All Combined | $765.64 | +$0.86 | +0.1% | +6.8% |
| Perth | All Houses | $788.86 | +$3.79 | +0.3% | +6.8% |
| Perth | All Units | $747.05 | -$4.12 | -2.5% | +6.5% |
| Perth | All Combined | $779.17 | +$2.03 | -0.3% | +6.7% |
| Adelaide | All Houses | $696.39 | -$2.96 | -1.6% | +7.5% |
| Adelaide | All Units | $583.40 | +$6.32 | -1.0% | +3.5% |
| Adelaide | All Combined | $667.30 | -$0.20 | -1.8% | +6.0% |
| Canberra | All Houses | $817.77 | -$6.72 | +2.7% | +5.4% |
| Canberra | All Units | $621.87 | +$1.77 | -0.4% | +4.9% |
| Canberra | All Combined | $681.15 | +$1.50 | 0.0% | +4.5% |
| Darwin | All Houses | $850.23 | +$4.18 | -0.4% | +15.9% |
| Darwin | All Units | $663.56 | -$10.09 | -0.6% | +8.3% |
| Darwin | All Combined | $752.73 | -$6.13 | -1.6% | +12.3% |
| Hobart | All Houses | $651.61 | +$3.71 | -0.1% | +4.2% |
| Hobart | All Units | $536.55 | +$6.45 | +1.6% | +2.9% |
| Hobart | All Combined | $617.65 | +$1.87 | 0.0% | +3.9% |
| National | All Houses | $769.35 | -$0.50 | -0.3% | +7.3% |
| National | All Units | $760.32 | -$1.31 | -1.3% | +6.8% |
| National | All Combined | $765.70 | -$0.84 | -0.7% | +7.1% |
| Cap City Average | All Houses | $791.26 | +$0.93 | +0.2% | +8.0% |
| Cap City Average | All Units | $680.22 | +$0.10 | -1.0% | +5.0% |
| Cap City Average | All Combined | $737.65 | +$0.16 | -0.7% | +6.6% |
Average advertised weekly rent across all listings available during the week, Ripehouse Advisory rental listings database. Week runs Monday to Sunday; capital cities defined by GCCSA boundaries.
General information only. It does not take your objectives, financial situation or needs into account, and nothing here is legal, financial, taxation or investment advice specific to your circumstances.