News · 28 September 2026 · 5 min read
The Budget still lets him negatively gear. Only on the house he wasn't going to buy.
He is 41. He owns his home, and one investment property: an older three-bedroom brick house in a middle-ring suburb he bought in 2022. After rent, it costs him about $160 a week to hold.
He is 41. He owns his home, and one investment property: an older three-bedroom brick house in a middle-ring suburb he bought in 2022. After rent, it costs him about $160 a week to hold.
He has spent three years building the equity for the second one. He had a shortlist. All established houses, all on streets where owner-occupiers outbid investors on a Saturday morning.
Then the Budget landed. Then the brochures started arriving.
He is a composite, drawn from the questions we have received since the Budget. The figures are his, not a headline's.
### The question he sent us
*"I already lose money on my first rental. I was about to buy a second, an older house near good schools. Now I'm told that from July 2027 I can't claim the loss against my wages, but if I buy a new build I can, and I keep the 50 per cent CGT discount as well. A salesman has already sent me a floor plan. Is the Budget telling me to buy the new one?"*
### The answer: yes, it is. That is the problem.
Here is what the Budget does, as set out by Property Update on 28 September.
From 1 July 2027, negative gearing will generally be limited to newly constructed residential properties.
If you buy an established home after the Budget announcement, you will no longer be able to deduct rental losses from your salary once the rules take effect. The losses are not deleted. They are deferred, carried forward and applied against future residential property income or capital gains.
Properties held before the announcement are grandfathered. His first rental is untouched.
The 50 per cent capital gains tax discount for individuals, trusts and partnerships is replaced with cost-base indexation and a minimum 30 per cent tax rate on real capital gains.
New residential property gets the softer treatment. Buy an eligible new build and you keep negative gearing, and you can choose between the current discount and the new indexation.
So yes. The tax system now has a preference, and it prefers the new estate over the old street.
### The rule almost nobody puts in the brochure
The concession is attached to the buyer, not the house.
On the day he settles, he is the only class of buyer who receives it. On the day he sells, that dwelling is no longer new. Property Update puts it plainly: the next investor who buys it may not receive the same tax treatment, which could reduce the depth of the resale market and affect what future buyers are willing to pay.
Read that again with money in mind. He buys at a price that includes the tax break. He sells into a market where the tax break has expired.
The same article lists what usually rides along with a new build: a developer's margin and marketing premium, areas with large amounts of similar stock, limited land value, weak owner-occupier demand, construction delays, builder insolvency and settlement valuation shortfalls.
None of that appeared in the floor plan he was sent.
Now hold the established house next to it. No negative gearing against his wages from July 2027. That is real, and for the first few years it makes the cash flow harder. But the loss is carried forward, not lost. It is a holding-cost question. It is not a question about what the house is worth, or who will want it in twelve years.
### The market this is happening in
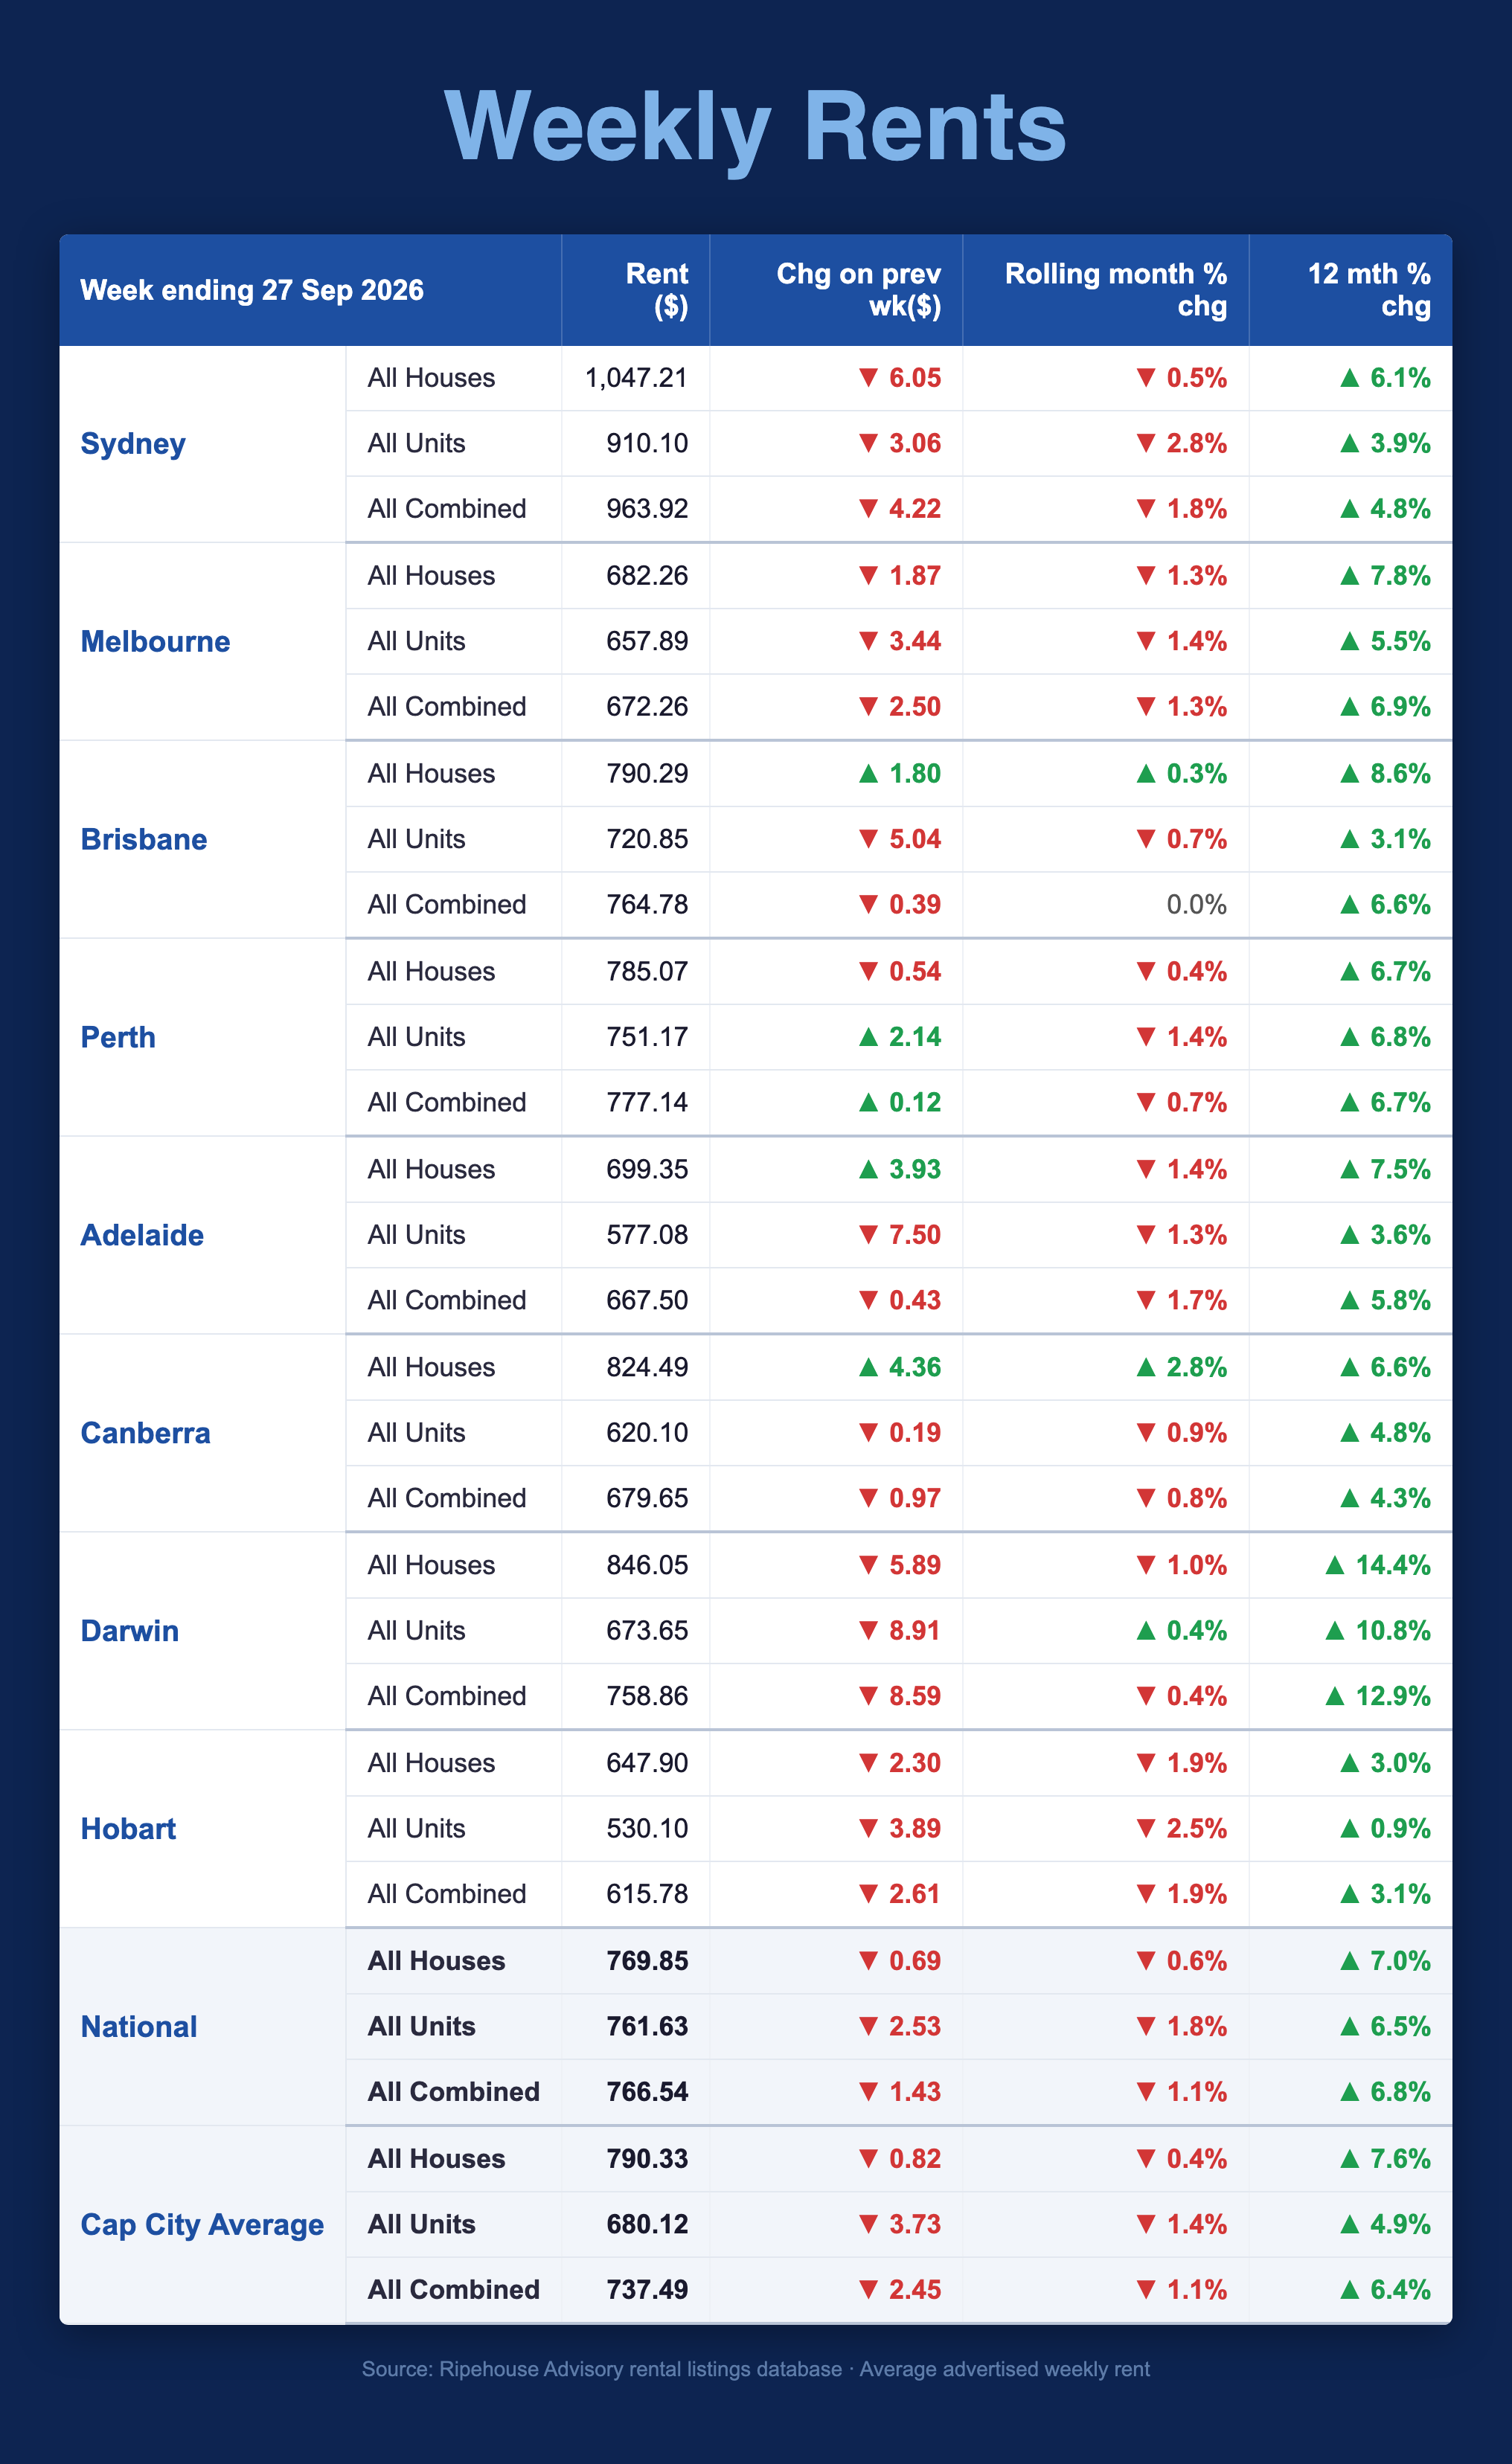
SQM Research puts the national vacancy rate at about 1.3 per cent, with asking rents up more than 7 per cent over the year.
Australia is expected to deliver about 980,000 new dwellings over the five-year Housing Accord period, roughly 220,000 short of the 1.2 million target. Net supply will be lower again, because some new construction replaces homes that were demolished.
The government estimates its reforms will add less than $2 a week to the median rent. That is a model. The author of the piece does not believe it. Nobody actually knows how thousands of individual investors will respond over a decade, and the honest position is to say so.
What we do know is that most tenants in this country live in homes owned by ordinary people with one or two properties. Make that harder and some of them stop.
### What it means for you
If you already own, the property you hold is grandfathered. Nothing changed for it.
If you plan to buy established after the rules start, you are making a cash-flow decision with a thinner buffer. Model it before you sign, with your own tax adviser, not with a salesperson's spreadsheet.
If you are being shown a new build, ask one question: what is this worth to the buyer who does not get the concession? If nobody can answer, you have your answer.
And remember that suburbs are not the unit of analysis. Two streets in the same suburb can be having completely different outcomes right now, and a tax concession does not know which one you are on.
### The Ripehouse reframe
This is a structure problem, not a discipline problem, and it is fixable.
The Budget did not change what makes a property grow. Land, scarcity, owner-occupier appeal and the street it sits on did the work before July 2027 and will do the work after. What changed is the order you buy in, how you hold, and how much buffer you carry while the losses sit on the books.
That is why we do not sell property and take no developer kickbacks. Right now, that matters more than usual, because the Budget just handed a marketing line to everyone who does.
We don't ask you to take our results on faith. We publish them, including the portfolios that underperformed. Across 997 client portfolios since 2021, the median has grown 19.0 per cent a year on a 5-year rolling basis, against about 4.3 per cent nationally.* Past performance is not a guarantee of future results.
He does not have to choose the house the tax code likes. He has to choose the house the next buyer will want, then structure around the rest.
15-minute Legacy Sequence Diagnostic: ripe.house/4bV7I8u. No pressure. No obligation. Just a clearer picture than you had before.
*National benchmark: CoreLogic/Cotality. This article is general information only and is not personal financial, tax or legal advice.
General information only. It does not take your objectives, financial situation or needs into account, and nothing here is legal, financial, taxation or investment advice specific to your circumstances.