News · 21 September 2026 · 5 min read
He paid his rent on time for six years. He is still being moved out.
New Real Estate Industry Partners data shows 45.4 per cent of Victorian unit renters handed a notice to vacate are being moved out because the owner is selling or moving in - not because they are behind on rent - up from less than a third a year ago. The cheapest rental stock is the stock leaving the market, and the replacement tenant pays up to 9 per cent more. Here is what that means for anyone underwriting a specific unit, and the street-level checks we run before buying one.
New Victorian eviction data, released this week by Real Estate Industry Partners, shows something that should stop any investor mid-scroll. Almost half of the unit renters being handed a notice to vacate in this state are not behind on their rent. They are being moved out because the owner is selling or moving in.
The person
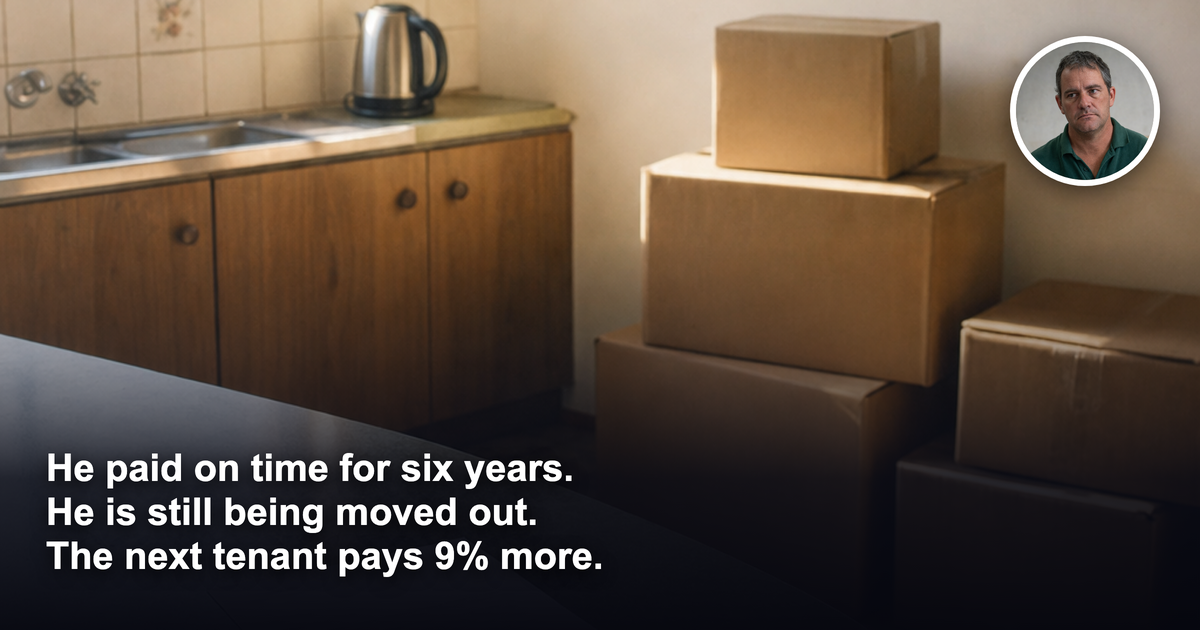
Picture a man in his mid-forties in an older brick walk-up in Melbourne's middle ring. He is a composite — an illustration, not a real person, and not connected to anyone named in the reporting — but his situation is now common enough to be measured.
He pays about $480 a week. He has paid it on time for six years. He has never been in arrears, never been to the tribunal, never had a complaint. Last month the notice arrived anyway. The owner is exiting.
He has done nothing wrong, and there is nothing he can do differently. That is what makes this a fairness question rather than a market question.
The question
If a tenant can be moved out of the cheapest housing in the state for reasons that have nothing to do with the tenant, what actually determines whether a rental property holds a tenant, holds a rent, and holds its value?
The answer, with the numbers
The REIP figures cover notices to vacate in the year from August 2025 to July 2026.
- 37.8 per cent of all notices to vacate were for tenants failing to pay rent.
- Almost a quarter were because the landlord wanted to sell or move into the home.
- For houses, the balance skews hard to arrears: 54 per cent of tenants were shown the door for non-payment.
- For units, the share of evictions driven by the owner selling or moving in has surged to 45.4 per cent — up from less than a third a year earlier.
Read those last two lines together. In houses, the pressure point is the tenant's budget. In units, it is the owner's exit.
REIP chief executive Sadhana Smiles put the consequence plainly: "And it's the most affordable housing that's being lost … and that's really concerning." She described the mix of Victorian land tax increases, tighter landlord regulation, federal changes to negative gearing and capital gains tax settings, rising interest rates and falling values as "a really perfect storm situation."
Then there is the number that matters most to an investor. When a tenant changes over, the incoming tenant pays a premium: typically 4 per cent more in a house, and up to 9 per cent more in a unit.
On our composite's $480 a week, a 9 per cent turnover premium is about $43 a week — roughly $2,236 a year — charged to whoever comes next, for the same flat, on the same street.
That is the injustice in one line. The cheapest homes are the ones leaving the rental pool, and the people who replace the displaced tenant pay the most for the privilege.
Tenants Victoria chief executive Jennifer Beveridge described what the arrears half of that data looks like from the inside: tenants who come up short "have already made cuts to every other part of their budget," and "may go without heating, kids' supplies, haircuts or weatherproof shoes."
Victorian households are already spending about 33 per cent of median household income on rent. Arrears cluster in Melbourne's west — Truganina, Wyndham Vale and Tarneit — all newer estate areas. Australian Bureau of Statistics lending data shows investor loans in Victoria have declined significantly this year, which is the supply side of the same story.
What it means for you
A headline writer reads that data and concludes investors are leaving Victoria. That is the lazy read, and it is not the useful one.
Here is the useful one. Two unit blocks can sit two streets apart, carry the same land tax regime, the same tenancy law and the same interest rate, and produce completely different outcomes — because tenant depth, turnover risk and exit liquidity are street-level facts, not state-level facts.
Nothing in the REIP release tells you which street. That is the work.
At Ripehouse Advisory we would not try to answer this from a state average. We would test the specific asset:
- Achieved versus advertised rent on that exact street, because the 9 per cent turnover premium is only collectable where a real tenant actually signs at that number. Advertised rent is a hope; achieved rent is a fact.
- Street-level vacancy and heatmaps, because a vacancy rate for a postcode can hide a saturated pocket three hundred metres wide.
- Days on market for that exact stock type — two-bedroom walk-up units, not "units", and certainly not "property".
- Approved-but-unbuilt competing supply within walking distance, because approvals that have not been completed are the rent competition that has not arrived yet, and the national pipeline data says a great many approvals are still stuck short of completion.
- Buyer depth on exit, because in a market where owners are the ones leaving, the question of who buys this from you is not academic.
- R-Score, which ties those measures together into one comparable street-level read rather than six separate hunches.
The reframe
The story in the data is not that residential property has stopped working. It is that state-level averages have stopped being a usable guide, and that the difference between a good asset and a bad one is now measured at the street, not the state.
An investor who buys the right unit, on the right street, with real tenant depth and a real achieved rent behind it, is not the villain of this data. They are the reason the affordable rental survives on that street at all — and they are also the one most likely to hold the asset instead of adding to the notices to vacate.
More of our street-level analysis starts from the same place: headlines describe the average. The average is not for sale. A specific property on a specific street is, and that is the only thing worth underwriting.
General information only. It does not take account of your objectives, financial situation or needs, and property values and rents can fall as well as rise. The person described above is a composite illustration, not a real customer, and is not connected to any person named in the reporting cited. Dollar figures attached to that composite are illustrative.
For investors trying to underwrite a unit in this market, the hard question is whether the street can absorb turnover without losing rent or buyer depth, which is exactly what the webinar will help test using street-level data. Ripehouse Advisory webinar.
Frequently asked questions
Why are so many Victorian unit renters being given notice to vacate if they are paying rent on time?
The article says 45.4 per cent of Victorian unit renters given notice to vacate are being moved out because the owner is selling or moving in, not because they are in arrears. That share has risen sharply from less than a third a year earlier.
What does the data suggest is happening to the cheapest rental homes in Victoria?
The article says the cheapest housing is the stock leaving the rental market. In practice, that means affordable units are more likely to be lost when owners exit, which reduces the supply of lower-cost rentals.
How much more can the next tenant pay when a rental property turns over in Victoria?
According to the article, a new tenant typically pays about 4 per cent more in a house and up to 9 per cent more in a unit. The article says that can add around $43 a week on a $480 rent, or about $2,236 a year.
What should an investor check before buying a unit in Victoria?
The article says not to rely on state averages. Instead, it recommends checking achieved versus advertised rent, street-level vacancy, days on market for the exact stock type, approved-but-unbuilt competing supply, buyer depth on exit, and an R-Score.
Why does the article say street-level analysis matters more than state averages?
It says two unit blocks only streets apart can face very different tenant depth, turnover risk and exit liquidity, even under the same land tax, tenancy laws and interest rates. That is why the article argues the real risk is measured at the street, not the state.
General information only. It does not take your objectives, financial situation or needs into account, and nothing here is legal, financial, taxation or investment advice specific to your circumstances.